Tesla Beats Q3 2026 Delivery Forecasts With 486,532 Vehicles, but Energy Storage Growth Disappoints
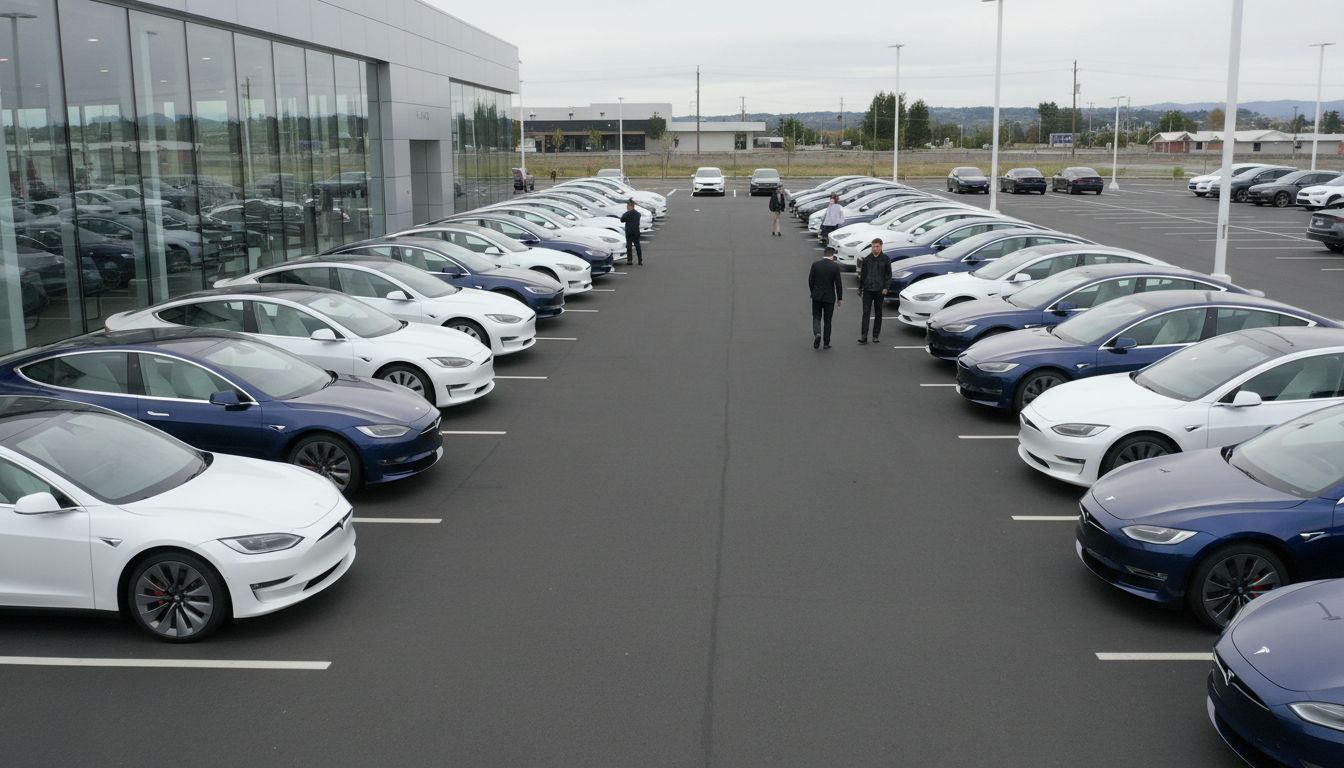
Tesla delivered 486,532 vehicles in the third quarter of 2026, beating Wall Street's consensus estimate of roughly 461,974 to 462,100 deliveries. The figure topped nearly every individual analyst projection, even as it represented a decline from the same period a year earlier.
Tesla Tops Delivery Estimates Despite Year-Over-Year Decline
Deliveries fell approximately 2.1% year-over-year, down from 497,099 vehicles in Q3 2025. Production for the quarter totaled 464,391 vehicles, meaning Tesla delivered 22,141 more vehicles than it built, a sign of inventory drawdown from existing stock. Model 3 and Model Y combined accounted for 98% of total deliveries, underscoring how dependent Tesla's volume remains on its two mainstream models.
Why Deliveries Slipped Year-Over-Year
Many analysts point to the expiration of the US federal EV tax credit after September 30, 2025, as the primary driver of the annual decline. Some reports suggest demand may have been pulled forward into earlier quarters as buyers rushed to take advantage of the credit before it lapsed, which could partly explain the softer year-over-year comparison.
A recurring theme in industry commentary is growing competitive pressure from Chinese EV makers, particularly BYD and Xiaomi, which continue to expand their global footprint. Broader coverage has also pointed to shifting consumer sentiment as a contributing factor, though the relative weight of these dynamics versus the tax credit expiration remains a matter of ongoing discussion rather than settled consensus.
Energy Storage Growth Falls Short of Expectations
Tesla's energy storage business deployed 13.7 GWh in the quarter, below analyst expectations of around 15.9 GWh. Still, the figure represents growth compared to 12.5 GWh a year earlier and 13.5 GWh in the prior quarter. The segment continues to be closely watched as a potential long-term growth driver for the company, even with this quarter's miss relative to projections.
Market Reaction and Year-to-Date Performance
Shares of Tesla rose roughly 5% following the delivery announcement, reflecting investor relief at the headline beat. Despite the pop, TSLA stock remains down approximately 21% year-to-date, a notable underperformance compared to other megacap technology companies. Year-to-date deliveries reached 1,324,681 vehicles, up 8.8% from the same period in 2025, suggesting that full-year volume growth remains intact even as quarterly comparisons have turned negative.
Profitability and Strategic Questions Ahead of Earnings
A volume beat does not necessarily resolve broader questions about Tesla's profitability, which several analysts and commentators continue to raise. A recurring concern among industry watchers is that delivery growth alone does not guarantee improved margins, particularly as competition intensifies and pricing pressure persists in key markets.
Some commentary has also questioned Tesla's strategic direction, noting the company's apparent move away from a previously discussed lower-cost vehicle in the $25,000 to $30,000 range in favor of heavier investment in autonomous driving technology. This remains a matter of opinion and strategic debate rather than a confirmed company policy shift, and views on whether this tradeoff will pay off are mixed among those following the company closely.
Tesla is scheduled to report full third-quarter earnings on October 21, 2026, when more detailed information on margins, profitability, and forward guidance is expected. Until then, the delivery and deployment figures offer only a partial picture of the quarter's financial performance.